

Canada’s rapidly growing biofuel sector is set to tighten global rapeseed supplies in 2026/27, as domestic processors absorb increasing volumes of seed to meet strong demand for canola oil and meal. Industry analysts warn that this shift will leave significantly less rapeseed available for export, even as production remains broadly stable.
The International Grains Council (IGC) currently pegs Canadian rapeseed output at 22.1 million tonnes for 2026/27 – close to last season’s level and around 600,000 tonnes higher than its September estimate.
However, the final figure will depend heavily on weather conditions, with harvesting in Saskatchewan and Alberta running behind schedule in early October.
Domestic consumption is forecast to rise sharply to 14.5 million tonnes, up from 13.1 million tonnes the previous year.
This surge reflects expanded crushing capacity and sustained demand for canola products, driven in part by the United States’ strengthened biofuel incentives. According to UFOP, the sector is benefiting from the revised US 45Z tax credit, introduced in early 2026, which rewards lower‑carbon feedstocks while tightening rules on imports from Mexico and Canada.
New GHG‑intensity calculation methods have further boosted the appeal of canola oil for biodiesel and HVO production.
This shift towards domestic processing is expected to reduce Canada’s exportable surplus. Research from Agrarmarkt Informations‑Gesellschaft (AMI) suggests rapeseed exports will fall to 7.8 million tonnes in 2026/27, down from 9.1 million tonnes last season.
Canada will remain a key global supplier, but its market share is likely to decline as more seed is diverted into domestic biofuel‑linked processing.
The trend underscores the growing influence of North American biofuel policy on oilseed markets, with Canada’s canola sector increasingly oriented towards supplying low‑carbon fuel pathways rather than international seed buyers.
LATEST NEWS
CONNECT WITH US
Latest Video
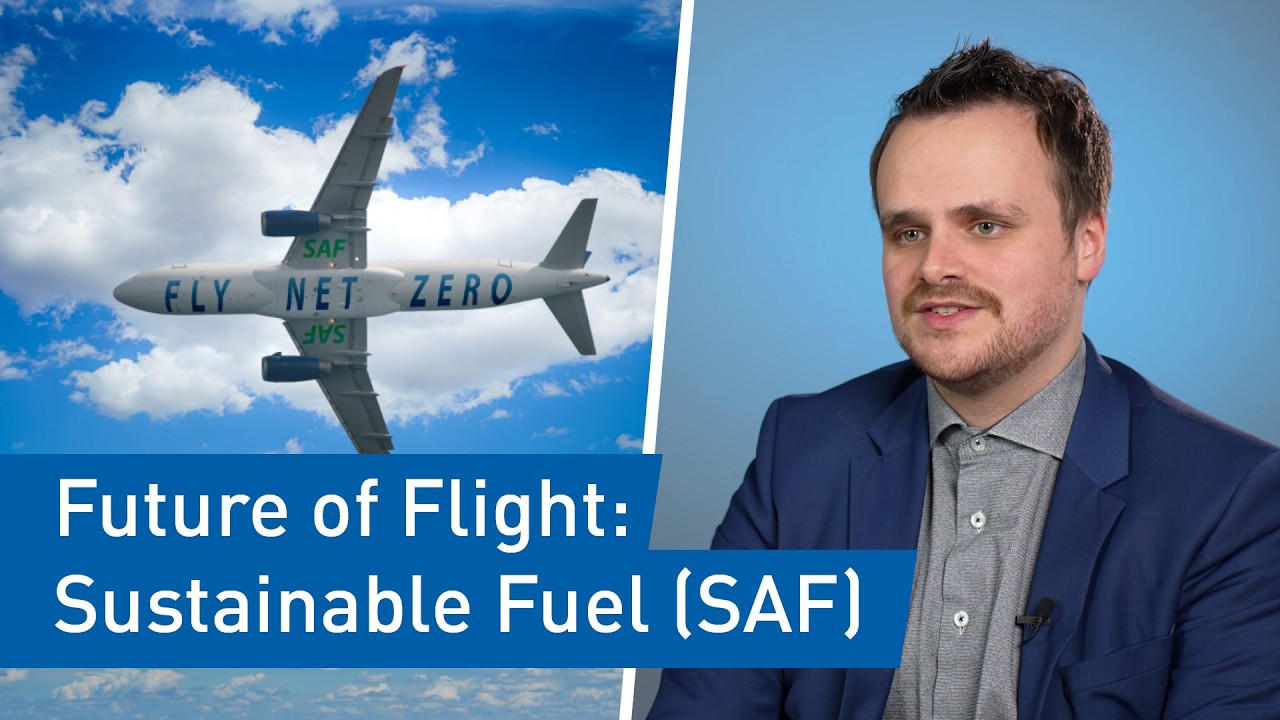
The hidden challenge scaling sustainable aviation fuel
In this interview, Yannick Farine provides valuable insights into the rapidly evolving market for sustainable aviation fuels (SAF). He highlights the key factors driving the rising demand, the current challenges in scaling up production, and the role that SAF will play in the future of aviation.

#Spain’s #Repsol is preparing to raise jet fuel output by 15–20% in response to mounting supply disruptions caused by the #Iran #war, which has unsettled global energy markets and tightened aviation fuel availability.
https://biofuels-news.com/news/repsol-to-lift-saf-output-as-iran-conflict-tightens-supplies/
#biofuels #SAF #aviation #output
#Nufarm Limited has expanded its strategic #partnership with #bp, reinforcing Nufarm’s ambition to scale sustainable biofuels and help meet growing demand for sustainable aviation fuel (SAF) and renewable diesel (RD).
https://biofuels-news.com/news/nufarm-extends-saf-and-rd-partnership-with-bp/
#biofuels #feedstock #aviation #SAF
#Thailand has moved to restrict #palm #oil #exports as domestic demand for #biodiesel surges, a trend closely linked to the ongoing conflict in the Middle East.
https://biofuels-news.com/news/thailand-restricts-palm-oil-exports-amid-rising-biodiesel-demand/
#biofuels #feedstock #demand #supply #SEAsia #war #conflict